


Article Summary: The Fed’s policy meeting sent a hawkish signal and hike expectations rose, widening market disagreements. This article analyzes the shift in the Fed’s stance, the possibility of hikes under inflation pressure, and the rational view that there is no rush to tighten, helping investors judge the market more calmly.
Light of Reason Under Hawkish Shadows: The Fed’s Hike Puzzle and Market Game Theory
After the Fed’s policy meeting last week ended, global financial markets were quickly surrounded by a new wave of tension. The sharp rise in hike expectations is quietly reshaping investor psychology and asset-pricing logic. But even as Wall Street firms revise forecasts and bet on a tightening path, one cautious and rational voice still stands its ground: not everyone believes the Fed will raise rates again this year.
1. Hawkish signals: reshaping the market landscape
At last week’s meeting, the Fed left the benchmark rate unchanged, and that decision itself did not trigger major market moves. What really caused a stir was the shift in policy tone. Nearly half of the Fed’s policymakers said publicly that they still expect at least one rate hike—and possibly several—this year. The market widely read that as a hawkish signal, and it quickly changed expectations for U.S. monetary policy.
From the policymakers’ comments, inflation is clearly the biggest concern. Fed Chair Warsh said after the meeting that inflation has stayed above target for five straight years and described persistent price pressure as a heavy burden on American households. That direct tone stands in sharp contrast to the more cautious language used in the past. More importantly, the statement removed the long-standing phrase suggesting an easing bias, marking a real policy turn.
2. Wall Street splits: aggressive hike expectations
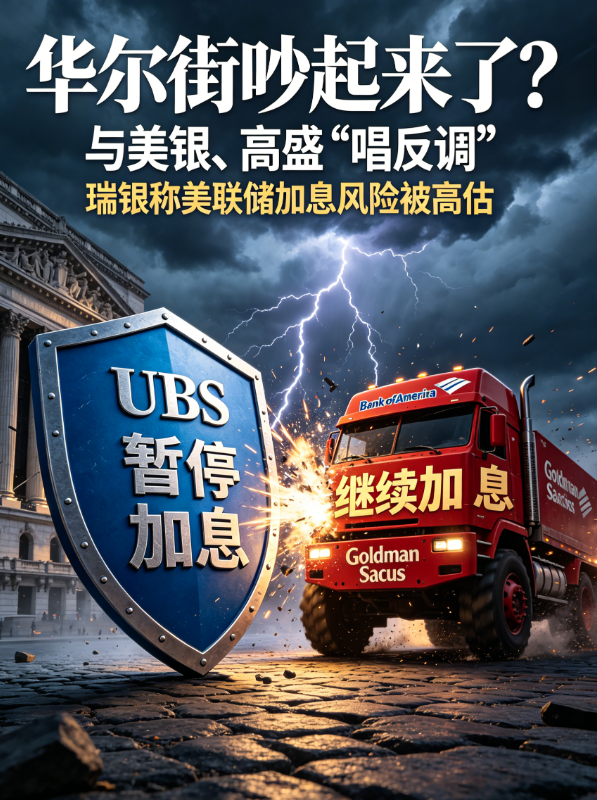
Faced with the hawkish signal, major Wall Street firms moved quickly. On June 22, Bank of America raised its forecast for Fed hikes this year from zero to three, citing a "clear deterioration" in inflation conditions. That is now the most aggressive hike view among major investment banks and shows how worried some market participants are about stubborn price pressure.
Deutsche Bank followed on June 19, forecasting two hikes this year. Its analysts said the current data do not yet justify three hikes, but the chance of two hikes has risen meaningfully. Meanwhile, Lindsay Rosner, head of multi-sector investing at Goldman Sachs Asset & Wealth Management, warned more directly that a July hike is "fairly likely," with a 50% probability. She stressed that the upcoming inflation data—especially the Personal Consumption Expenditures (PCE) report—will be key in pushing the Fed to act.
The dot plot shows the concern is not baseless. About half of Fed officials expect at least one more hike before year-end. As a result, 2-year Treasury yields rose quickly, and investors began to fully price in the possibility of a hike at the October meeting. All of this shows the market shifting from a "rates stay high for a long time" view to a "rates could go even higher" view.
3. UBS’s different take: rational judgment beneath the hawkish surface
In the middle of all the hike talk, UBS analysts offered a completely different view. In a June 22 report, the bank said the market may be seriously overestimating the risk of a hike. UBS argued that, while policymakers sound hawkish, the shift is not as aggressive as it looks.
First, UBS points out a key fact: many of the hawkish officials do not have voting rights this year. That means the market may be overplaying their real influence on policy decisions. In addition, the Fed is currently running a broad policy review, with five task forces working on communication, balance-sheet management, data sources, productivity and employment, and inflation assessment. UBS believes the Fed will remain cautious about changing rates until the review’s conclusions arrive later this year.
UBS also makes an external-factor argument: if the Strait of Hormuz remains open, the risk that energy prices keep driving inflation higher would fall significantly. UBS thinks the dot plot in future meetings may reflect this improvement, easing fears of additional hikes.
Based on that view, UBS keeps its base case unchanged: rates stay on hold through the rest of 2026, and easing resumes in early 2027. In other words, UBS not only does not expect a hike this year, it expects the next move to be a cut.
4. Inflation data: the key test for market direction
Among all economic indicators, inflation data is the most important variable. As the Fed’s preferred inflation gauge in the Powell era, the May PCE price index will be the key test of the Fed’s stance. Investors will watch core PCE especially closely for signs that price pressure is easing after the earlier energy shock.
If core PCE falls noticeably, it could ease fears of continued hikes and support the no-hike view held by UBS and others. If inflation remains stubbornly high, the hawkish camp will gain strength and more banks may join the hike forecast. In that sense, the upcoming data are not just a reflection of the economy—they may become the turning point for market sentiment over the next few months.
5. UBS strategy: lock in certainty in yields
In this uncertain policy battle, UBS gives a clear investment suggestion. If the market is indeed overpricing tightening by the Fed and other major central banks, then today’s yields on high-quality short- and intermediate-duration bonds become attractive.
"Based on our view, we recommend high-quality short- and intermediate-duration bonds to lock in attractive yields," UBS wrote. The core logic is simple: if the market’s hike expectations never materialize—or if cuts come instead—then current yield levels will prove relatively high. By locking them in now, investors can earn steady returns as the market reprices.
UBS is not the only firm that expects the next move to be a cut. Citi currently expects the Fed to cut rates in October and December 2026, then again in January 2027. The two banks differ on timing, but they agree on one core point: after a prolonged high-rate period, the Fed will eventually have to ease.
Conclusion: uncertainty inside certainty
Although the Fed meeting is over, the market turbulence it triggered is still going. On one hand, rising hike expectations are reshaping global asset allocation, and more Wall Street firms are joining the camp that expects a hike this year. On the other hand, UBS and others insist on a more rational reading and think the market is overreacting to the hawkish tone.
In this forecasting battle, what will really decide the outcome may not be Wall Street opinion, but the economic data that are about to arrive—especially inflation. Investors need to understand that markets are always uncertain, and interest-rate policy is one of the most complex and least predictable variables of all.
For investors facing such a divided market, UBS’s cautious stance may be the better model: do not blindly follow the crowd, but do not dismiss the signal either. Build a flexible and resilient asset-allocation strategy based on a full understanding of all sides. In a fog of monetary policy, patience and rationality matter more than trying to place a bet too early.
