


Article Summary: MWC Shanghai 2026 observations focus on 6G and satellite internet: integrated sensing and communications, AI-native, and space-air-ground convergence are converging; satellite networks are entering a stage of scale deployment and cost reduction, while terminals and ROI still need validation.
MWC Shanghai 2026: Observing the scaling and cost reduction of 6G and satellite internet
Recently, MWC Shanghai 2026 opened as scheduled. Unlike last year’s feverish atmosphere of dense 5G-A commercial orders, this year’s venue had a more cautious, pragmatic feel: the newly independent “6G Industry Ecosystem Zone” and the “Future Constellation” satellite area were both busy, but the industry was more focused on asking when technology would truly turn into cash.
In 6G, the three major paths—integrated sensing and communications, AI-native, and space-air-ground integration—are already consensus items, and chipmakers have even started pre-research and inventory planning early. In satellite internet, the “land grab” for orbital and frequency resources is basically over, and scale deployment plus cost reduction have become the new theme. Yet consensus stops at the technical level—terminal makers and investors are largely holding back, with the former waiting for killer apps and the latter unable to calculate the payback period. Even profitable international satellite players are finding the early civil market cultivation phase difficult.
When the financial bill for 5G investment has not yet been fully settled, 6G and satellite internet have collectively entered a transition period of “clear vision, hard monetization.” The technology path is narrowing, while the commercial exit looks broader and broader. Under real investment-return constraints, the industry needs a more practical answer than a grand narrative.
6G technology paths are converging, but the commercial loop is still being explored
Walking into the 6G Industry Ecosystem exhibition area in Hall N3 at MWC Shanghai, five sections—the Beijing 6G Laboratory overall area, communication enhancement, integrated sensing and communications, communication-compute-intelligence integration, and space-air-ground integration—present the core 6G technical vision in a clear and tangible way. Staff on site told reporters this is the first time in MWC Shanghai history that 6G has been given its own hall, sending a very clear industry signal: 6G has moved from conceptual discussion into a critical stage of system validation.
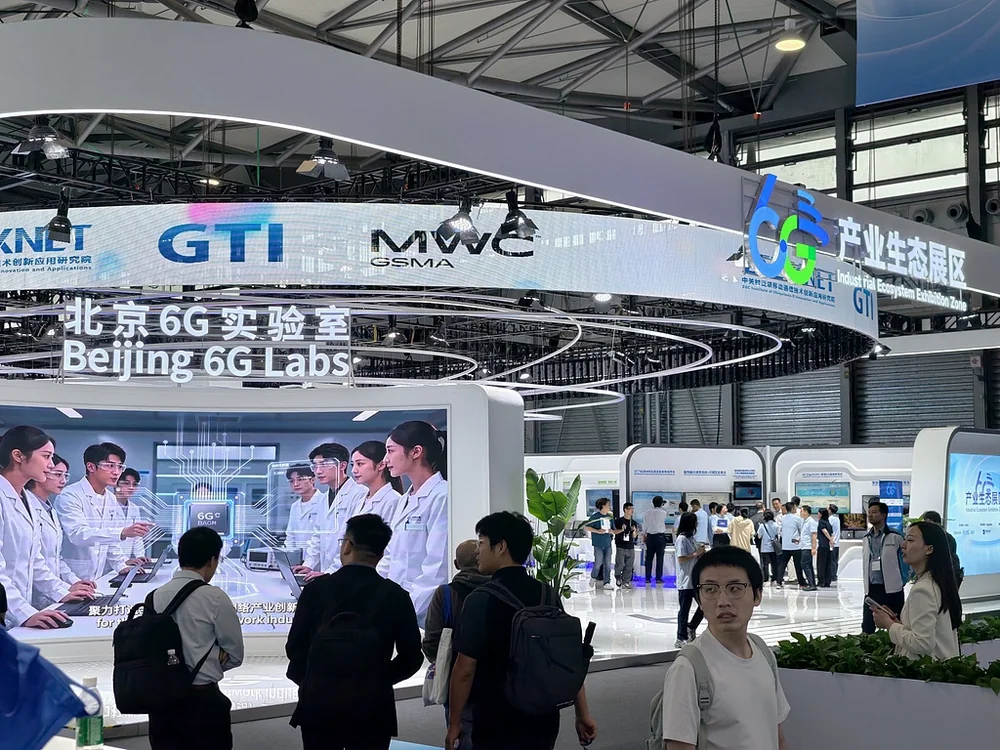
“If last year everyone was still arguing over what 6G should do, this year the debate is about how to do it, and what trade-offs to make,” a technical staff member from the Beijing 6G Laboratory overall area told reporters. Right now, the three enhancement paths—integrated sensing and communications, AI-native, and space-air-ground integration—have basically formed industry consensus, and key technologies such as terahertz communications and intelligent metasurfaces have already entered prototype verification.
The upstream supply chain is clearly accelerating its pace. At this exhibition, Qualcomm displayed an end-to-end 6G prototype system, Galaxy Space publicly showed its self-developed second-generation phone-direct phased-array antenna for the first time in the 6G Industry Ecosystem Zone, and vivo presented its 6G pre-research prototype and technical roadmap. According to reports, unlike Xiaomi, which focuses more on underlying transmission algorithms, and OPPO, which focuses on communication paradigm innovation, vivo’s display direction is more toward end-to-end systems and application landing—its complete 6G trial system covers the full chain including MR terminals, 6G terminal prototypes (UE), 6G base stations (RAN), and the core network.
On-site leaders from domestic chipmakers told reporters that their internal 6G pre-research team has doubled in size compared with last year, and the logic is clear: “If we wait until the standard is frozen to start, it will be too late—we must build technical reserves ahead of time.”
However, compared with upstream enthusiasm, terminal makers are relatively cautious. When reporters asked several phone brands about their 6G terminal plans in the 6G zone, most responses were “closely monitoring,” and there were few consumer-grade 6G product demos on display. In informal conversation, the 6G pre-research lead at one of the world’s top-five smartphone vendors said it is still hard to produce a clear commercial roadmap for a 6G phone. The main reason is not a lack of technical ability, but that the path for converting user needs and application scenarios on the terminal side is still under review. In his view, the experience gains from 5G have not yet been fully released, and the immersive holographic and multi-sensory scenarios envisioned for 6G are still some distance from mass consumer markets.
The investment community is equally cautious. During a break at the exhibition, reporters met an early-stage investor focused on TMT. After seeing multiple demos in the 6G area, he said that while the technology direction is impressive, from an investment standpoint the capital returns from 5G are still being digested, and the subsequent R&D and network-deployment scale for 6G will be huge. Exit cycles and return expectations currently lack sufficient data support. He admitted that at this stage he is mainly tracking and observing, and the timing for action still needs clearer commercial signals.
“Future Constellation”: the structure is taking shape, but the profit path still needs validation
Unlike the 6G area, which focuses on key technology validation, the first-time “Future Constellation” satellite industry zone presented a different rhythm—orbital structure is already taking shape, and participants are now entering a stage of fine-tuning resources and costs.
Domestic low-orbit broadband and narrowband constellation operators such as Commsat, Geespace, and Spacesail, along with international players like Iridium, all built sizeable booths. Commsat showcased real low-orbit satellite internet terminal devices for scenarios such as ocean-going vessels and desert mining areas; Geespace highlighted application cases of the Tiantong constellation in IoT; Spacesail engineers even connected live to show video-call testing based on the “Thousand Sails Constellation.”
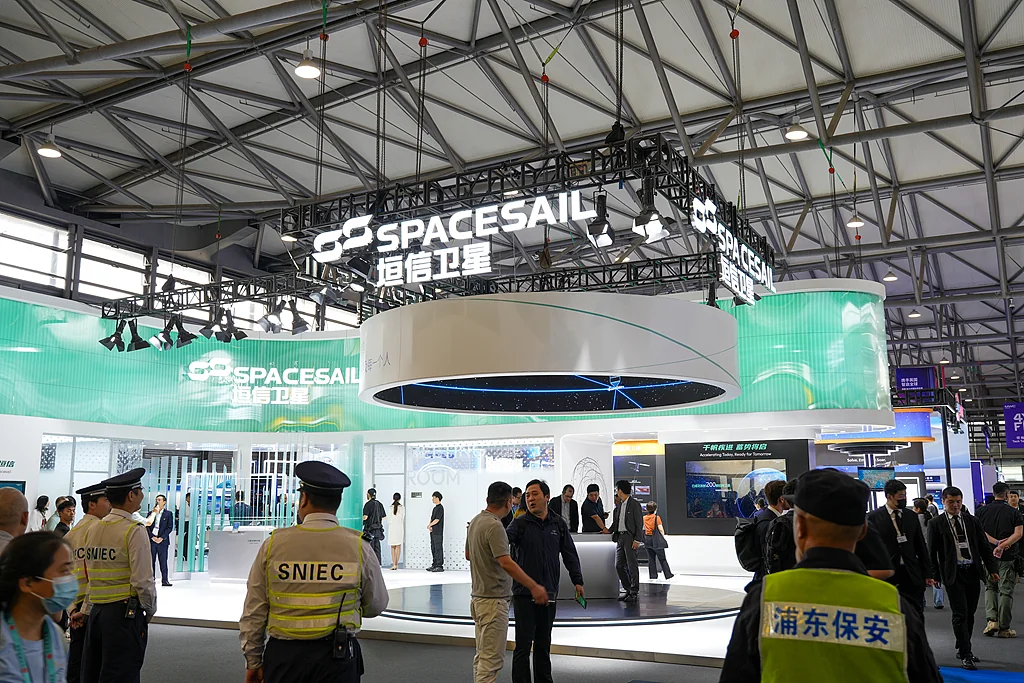
“The race for orbital and frequency resources in satellite internet is basically over; the key now is scale deployment and cost control,” a person from Geespace told reporters on site. He said the batch production cost of the company’s narrowband communication payloads is steadily declining, but he also noted that the user scale for satellite internet services has not yet reached break-even, and for at least the next few years, government and industry orders will remain the basic pillar of revenue.
In the path to profitability, terminal cost is a point worth watching. At antenna and module makers’ booths, reporters discussed bill-of-materials costs for satellite communication terminals. Interviewees generally said costs are falling rapidly and are now capable of integration into mainstream handset designs, but most did not disclose exact figures.
An Iridium business manager at the U.S. booth said Iridium has achieved positive cash flow thanks to narrowband voice and low-speed data services, but the traditional market is nearing saturation, so the next growth step must be in IoT and emergency communications. By contrast, domestic low-orbit broadband constellations are still in a catch-up phase focused on scale, and reaching break-even will require time and user accumulation.
